
Back to all blog posts

HR teams have always needed hard numbers to build a defensible benefits budget. In 2026, Finance is asking for the same numbers, because benefits spend has grown large enough to show up as its own line in headcount planning and renewal forecasting. Both groups are working from the same question: How much does a benefit program cost per employee, and how does that compare to what similar employers spend?
This guide breaks down the latest BLS data on the average cost of employee benefits, the typical ratio of benefits to salary, why the average package keeps getting more expensive, and what to budget for across mandatory, healthcare, and lifestyle benefits. It closes with a section for finance stakeholders and a calculator to model your own numbers.
The U.S. Bureau of Labor Statistics reports employer benefit costs per hour worked. To make those figures easier to use for budgeting, the estimates below convert them into monthly and annual costs based on a 35-hour workweek and 52 paid weeks per year. BLS's "civilian workers" figure combines private sector and state and local government employers, which is why the release also breaks out private industry and state and local government separately:
The same BLS release shows how employer compensation is divided between wages and benefits. Benefits account for 30.1% to 38.5% of total compensation, depending on the sector. Measured against wages and salaries alone, benefits add approximately 43% to 63% to an employer's salary costs.
For private industry employers, adding roughly 43% to wages provides a more accurate starting point for estimating fully loaded compensation than adding 30%. Actual costs will vary by industry, though the cost-effective employee benefits you choose can shift that ratio either way. One definitional note: BLS tracks supplemental pay, things like shift differentials, overtime, and nonproduction bonuses, as its own category separate from both wages and benefits, so check which bucket your own payroll data uses before comparing numbers directly.
Beyond the cost of the benefits themselves, employers also pay for the platform or vendor that administers them:
A PEPM fee is predictable, but a usage-based fee can swing with utilization, a distinction worth flagging to Finance early.
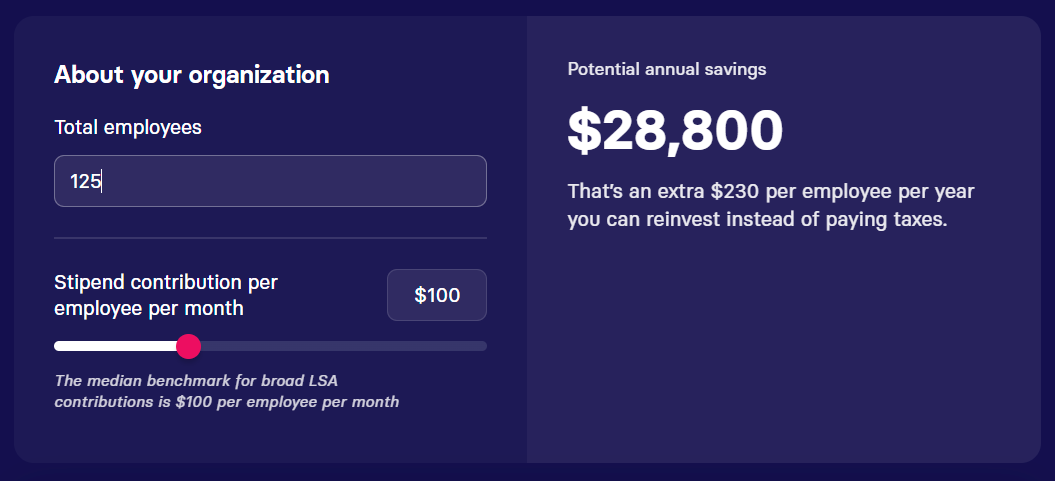
Three forces are driving costs higher heading into 2026.
Employees expect more from their benefits than they did five years ago. The pandemic reshaped expectations around flexibility and mental health support, and cost-of-living pressure has pushed employees to lean on employer support for everything from childcare to financial wellness. Employers with a narrow package have had to expand it to stay competitive.
Health insurance renewals remain a major driver of rising costs. Mercer's 2025 National Survey of Employer-Sponsored Health Plans, covering more than 1,700 employers and reported by Fierce Healthcare, found employers expect total health benefit costs per employee to rise 6.5% in 2026, the highest increase in 15 years, or closer to 9% without cost-management measures. More than half, 56%, plan new cost-cutting measures for 2026, up from 48% the year before.
Remote and hybrid work continue to reshape what a competitive benefits package looks like. The BLS American Time Use Survey for 2025 found that 35% of employed people did some or all of their work at home on days they worked, while 70% worked at their usual workplace. The split isn't even across roles: 51% of people with a bachelor's degree or higher worked from home some days, compared with just 19% of those with only a high school diploma. Employers competing for degree-heavy roles are budgeting for work-from-home and coworking stipends that a purely on-site workforce wouldn't need.
Benefits budgets generally break into three buckets: benefits you're legally required to provide, healthcare benefits, and lifestyle benefits that support retention and engagement. (Retirement contributions, like a 401(k) match, fall under retirement and savings, a separate BLS category usually budgeted on its own and outside the scope of this guide.)
Every U.S. employer budgets for a baseline set of legally required benefits, most of which land on the books as payroll taxes:
A March 2026 BLS release also breaks out healthcare-specific costs. Employers spent the following on health insurance as a share of total compensation. (These figures cover insurance premiums; they don't include what employees and employers additionally set aside pre-tax through a health savings account (HSA) or a healthcare FSA, which shifts part of the cost of care without changing the premium line below.)
Disability insurance (short-term and long-term combined) is a smaller line item: $0.14 per hour (0.3%) for civilian workers, $0.15 (0.3%) for private industry, and $0.10 (0.2%) for state and local government. Life insurance is typically a smaller line as well, often bundled into the same group insurance package as health and disability coverage. Access to short-term disability still varies by employer size, per BLS's separate Employee Benefits in the United States survey: 31% at private-industry establishments under 100 workers, 53% at 100 to 499, and 68% at 500 or more.
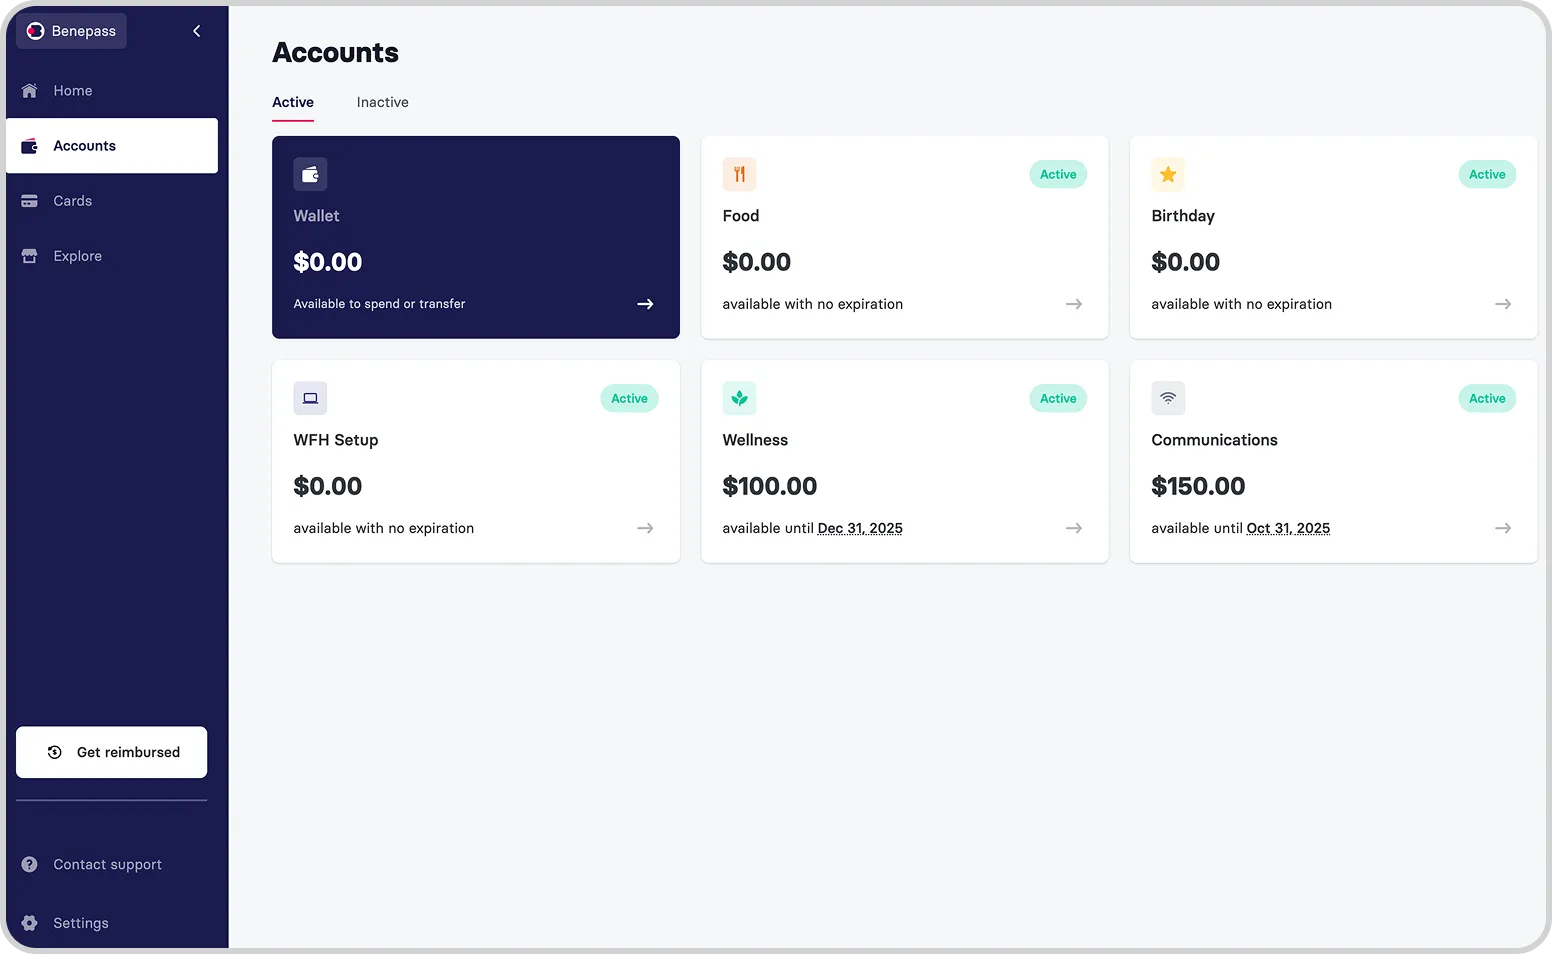
Lifestyle spending accounts are now the default way employers fund flexible, non-healthcare fringe benefits, and the 2026 Benepass Benefits Benchmarking Report shows employers rebalancing that spend rather than just increasing it. Broad LSA contributions fell 33% year over year to $800, and Fitness and Wellness fell roughly 20% to $600, while targeted categories picked up the difference: Professional Enrichment rose 50% to $1,800 and Commuter rose 33% to $2,400. Current median annual employer contributions by category:
Employers are also offering more categories at once. Rewards and Recognition is now the fastest-growing LSA type, offered by nearly 20% of employers, up from 7% the year before. Our guide to lifestyle spending accounts covers how to structure that mix.
Nine factors typically drive variation in cost from one employer to the next:
Eight practices help employers get more value out of the same benefits spend:
Getting these fundamentals right also affects employee retention and the cost of turnover, often a bigger number than the benefits budget itself.
HR builds the benefits program, but Finance owns the forecast, and the numbers above translate directly into planning inputs.
Start with benefits cost as a per-FTE line. Multiplying the hourly BLS rate by expected headcount growth gives Finance a defensible per-FTE benefits line for the next budget cycle, rather than a rough percentage-of-payroll estimate. Translating that hourly figure into a monthly or annual line item, the way this guide does above, makes it usable in a standard budget template instead of a format only HR reads comfortably.
Utilization data matters just as much as the sticker cost at renewal. A benefits line that costs more this year but shows rising engagement and fewer forfeited dollars is a different conversation with leadership than one that costs more with flat or declining utilization. Our lifestyle spending account ROI guide and our guide to increasing benefits utilization cover how to build and strengthen that case before your next renewal.
Benchmarks are a starting point, not a substitute for your own numbers. Benepass helps HR and Finance teams model per-employee benefits costs and consolidate point-solution spend into one platform with clear reporting for budget season. Explore the full feature set or book a demo to see how your program compares.
Nationally, benefits make up 31.6% of total compensation for civilian workers, 30.1% for private industry workers, and 38.5% for state and local government workers, per the BLS ECEC release for March 2026.
As a starting point, private industry employers spend an average of $14.01 per hour, or roughly $25,498 per year, per employee on benefits. Adjust based on company size, industry, location, and how broad your package is.
Yes. Larger employers often secure better per-employee rates on healthcare and platform fees, but they also tend to offer a broader mix of lifestyle benefits, which can offset those savings. Access to specific benefits like short-term disability also varies by size, from 31% at the smallest employers to 68% at the largest.
