
Back to all blog posts

According to the U.S. Bureau of Labor Statistics, as of March 2025, only 14% of civilian workers had access to flexible benefits. Most employees are still locked into rigid packages that don't reflect how they actually live and work. As workforces become more distributed and demographically diverse, that mismatch shows up in low utilization, disengagement at open enrollment, and benefits spend that doesn't move the needle on employee retention.
A flexible benefits scheme is the structural answer to that problem. Instead of enrolling everyone in the same health plan, FSA, or wellness perk, you give employees a defined budget or set of benefit options and let them allocate funds based on their own priorities. The result is a program that works harder for your workforce without necessarily costing more.
A flexible benefits scheme is an employer-sponsored program that lets employees choose from a menu of benefits rather than receiving a fixed, one-size-fits-all package. You define the rules, budget, and eligible categories. Your workforce decides how to use them.
In practice, a flexible benefits scheme can take several forms. Some employers build a cafeteria plan under IRS Section 125, which lets employees pay for certain benefits with pre-tax dollars. Others layer in lifestyle spending accounts (LSAs), health reimbursement arrangements (HRAs), or voluntary insurance products to expand choice beyond traditional health and welfare benefits.
The model is gaining traction with mid-market and enterprise HR teams because it addresses a straightforward reality: Your workforce doesn't all need the same things. With average annual premiums for family coverage reaching $26,993 in 2025, according to the KFF Employer Health Benefits Survey, giving employees more control over how their benefits dollars are spent has become a practical cost management strategy, not just a perk.
Most HR teams build a flexible benefits scheme by layering multiple models together rather than choosing just one. According to Benepass's 2026 Benchmarking Report, 38% of employers now offer both LSAs and pre-tax benefits, up from 33% the year prior. Each model carries its own tax treatment, eligible expense categories, and compliance requirements. Understanding the differences helps you design a program that balances employee choice with administrative feasibility.
Benepass supports all of these model types on a single platform and card, giving you one system to configure and fund programs rather than managing multiple point solutions.
A Section 125 cafeteria plan lets employees pay for qualified expenses with pre-tax dollars through payroll deduction, reducing taxable income for both employees and employers. The two most common account types are:
Both require employees to elect a contribution amount during open enrollment, and funds are subject to use-it-or-lose-it rules, though you can offer a $680 carryover or a grace period of 2.5 months for FSAs. For 2026, contribution limits are:
The tax savings are real: every dollar contributed reduces taxable income, and you save on FICA taxes as well. The trade-off is administrative complexity around elections, claims processing, and annual limit tracking. If you're building a cafeteria plan for the first time, start with a healthcare FSA and add DCFSA once you have a clearer picture of employee demand for dependent care support.
An HSA is a tax-advantaged savings account available only to employees enrolled in a high-deductible health plan (HDHP). Funds roll over year after year with no use-it-or-lose-it penalty, and employees own the account even if they leave your organization.
HSAs carry a triple tax advantage:
For 2026, contribution limits are:
Many employers contribute a set amount to each employee's HSA as part of their total rewards package, which increases perceived benefit value without adding to fixed premium costs.
HSAs work best for employees who can manage higher deductibles and want to build long-term healthcare savings. You'll need to confirm HDHP eligibility and coordinate with your health plan vendor, but the administrative overhead is lighter than FSAs because employees manage their own accounts.
An HRA is an employer-funded account that reimburses employees for qualified medical expenses such as deductibles, copays, and coinsurance. Certain HRA types (ICHRA, QSEHRA, and EBHRA) can also reimburse health insurance premiums, but most integrated group HRAs cannot.
Only the employer contributes. You set the reimbursement limit, define eligible expenses, and decide whether unused funds roll over or expire.
Common HRA types:
Employer contributions to an HRA are tax-deductible, and reimbursements are tax-free to employees when used for qualified expenses. HRAs come with strict compliance requirements under the ACA, ERISA, and HIPAA, so plan documentation and nondiscrimination testing are non-negotiable. One key constraint: HRAs can't be paired with an HSA unless structured as a limited-purpose or post-deductible HRA.
An LSA is an employer-funded benefit that reimburses employees for expenses you define, such as gym memberships, home office equipment, professional development, or mental health services. You set the annual allowance (typically $250 to $2,000 per employee), define eligible categories, and decide whether funds roll over or reset each year.
Unlike pre-tax accounts, LSAs are taxable to employees, which makes them administratively simpler but means you'll need to account for gross-up costs when budgeting. Employer stipends work similarly but are structured as fixed monthly or quarterly payments rather than reimbursement accounts, covering categories like remote work, wellness, or commuting.
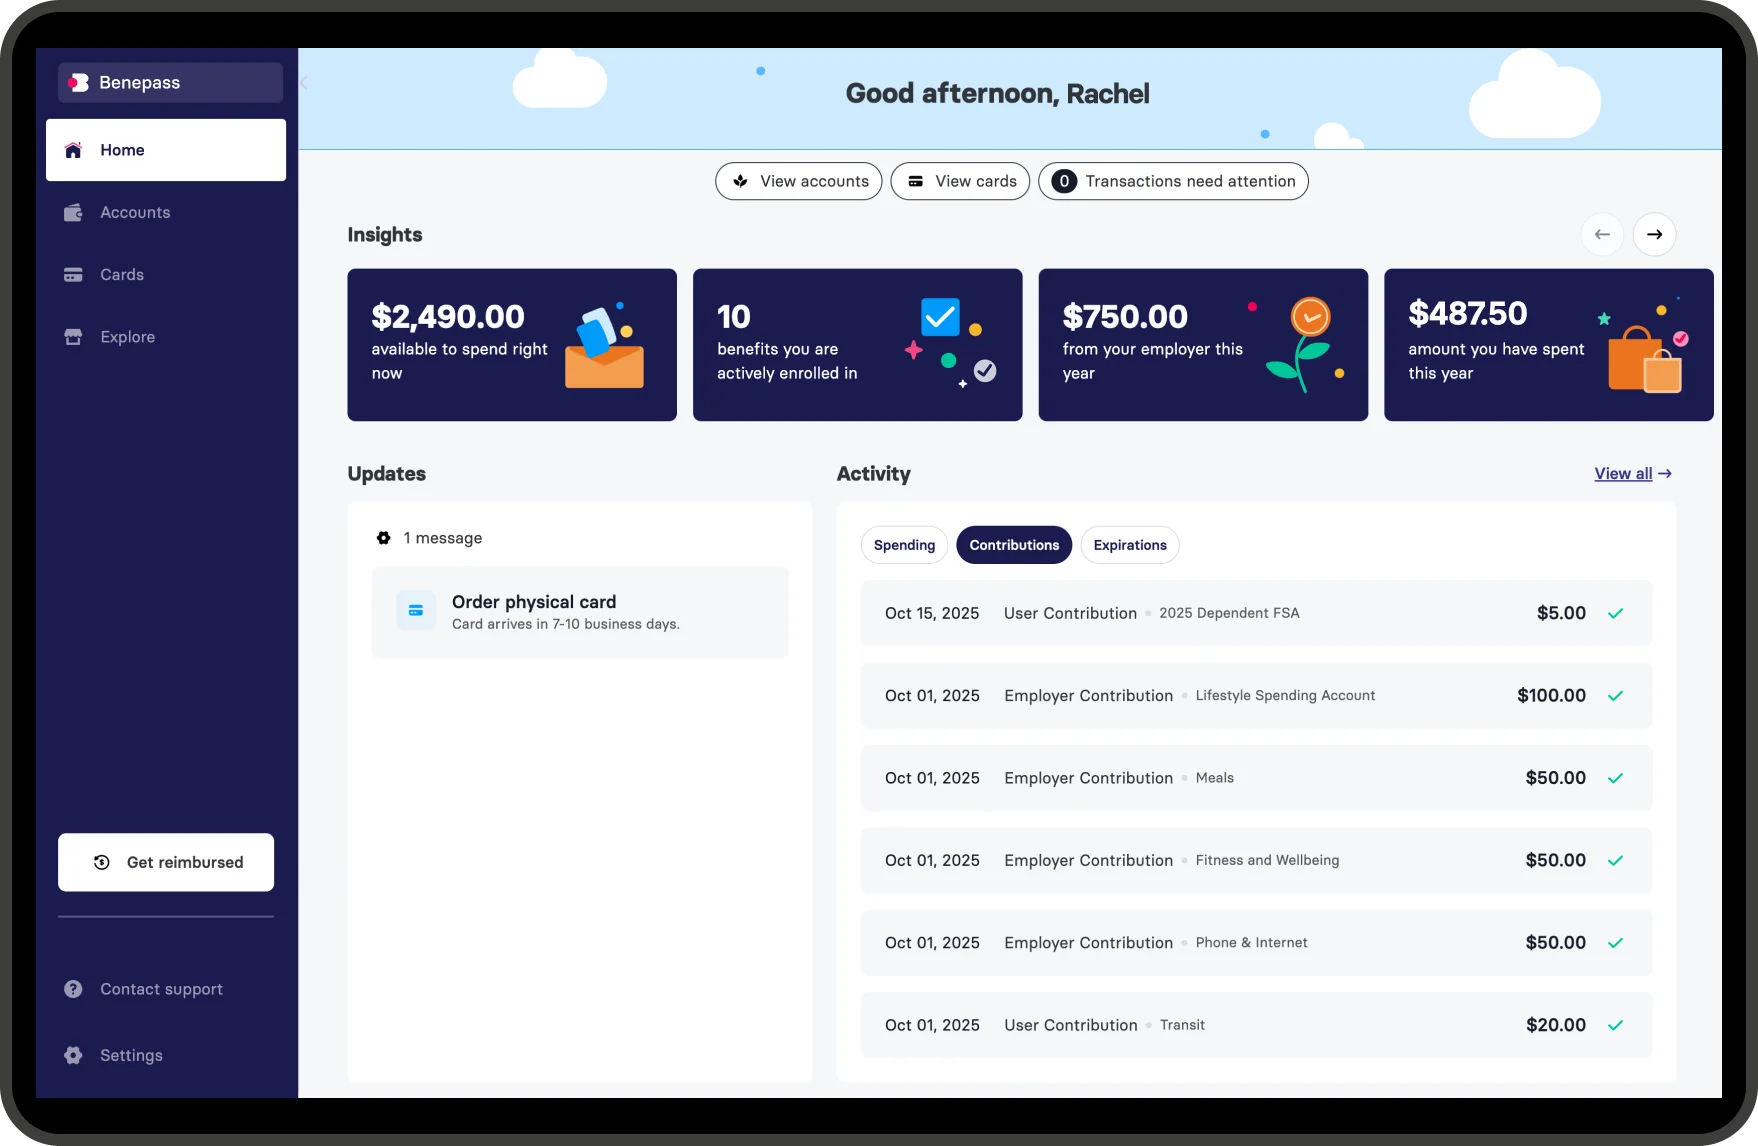
LSAs and stipends are especially practical for distributed teams because they let you offer meaningful support without tying employees to specific vendors or locations. They're also a low-commitment way to test new benefit categories before building a formal pre-tax program. For more, see using LSAs to create agile employee benefits.
Voluntary benefits are insurance products employees purchase through payroll deduction at group rates you negotiate. Common options include critical illness insurance, accident coverage, pet insurance, legal services, identity theft protection, and supplemental disability or life coverage beyond your core offering.
You don't fund voluntary benefits directly, but you sponsor the program by selecting vendors, managing enrollment, and facilitating payroll deductions. This expands your benefits menu without increasing your direct costs and gives employees access to coverage they might not find or afford on the individual market.
The main challenge is enrollment complexity: offering five or six voluntary products alongside core benefits can overwhelm employees. A unified benefits platform helps by presenting all options in one place, so employees can compare coverage without navigating multiple vendor portals.
Start by deciding who can participate and how much you'll allocate:
Next, establish policy guardrails: which benefit categories are mandatory, which are optional, and what documentation you'll require for reimbursements. If you're including pre-tax accounts, confirm your plan document language aligns with IRS rules and your payroll deduction schedule.
For cafeteria plans, decide whether to offer a grace period or carryover for unused FSA dollars. These decisions directly affect cost predictability, compliance risk, and how fair the program feels to employees.
Use employee surveys, utilization data, and demographic analysis to identify which benefits will drive the highest employee engagement. A workforce with many parents may prioritize dependent care FSAs and childcare stipends. A distributed team may value home office allowances and coworking memberships more than traditional voluntary insurance.
Your menu should balance core benefits (like health, dental, vision, or retirement plans) with flexible options that reflect how your people actually live and work. The goal is enough choice to feel personalized without overwhelming employees during enrollment. Tiered budgets based on job level or family status can improve perceived fairness, but document your rationale clearly so the structure feels transparent rather than arbitrary.
Vendor selection is where many HR teams lose weeks to discovery calls and integration scoping, only to find their chosen vendor can't support all the account types they need. If you're offering FSAs, HSAs, HRAs, and lifestyle stipends, you shouldn't need four different systems, four different cards, and four separate data feeds.
Find a vendor, like Benepass, that consolidates pre-tax, lifestyle, and wellness programs onto one card and one administrative system, reducing the vendor sprawl that drives up cost and administrative burden.
When evaluating any vendor, confirm:
Also ask how the system handles mid-year status changes, COBRA, and leave of absence, since those edge cases are where disconnected systems create the most friction.
Even a well-designed flexible benefits package will underperform if employees don't understand how to use it. Most HR teams need 60 to 90 days to complete vendor onboarding, payroll integration testing, and manager training before open enrollment begins.
Your open enrollment communications should clearly answer four questions:
Use multiple channels to reach your workforce, and schedule live QA sessions employees can attend or watch later. Test your enrollment process with a small pilot group before opening it to everyone. Catching integration errors and confusing language early is far less costly than troubleshooting them during the final week of open enrollment.
Once your flexible benefits scheme is live, the right metrics tell you whether the program is delivering value:
Measure employee satisfaction through pulse surveys or benefits-specific feedback. Ask whether employees understand their options, feel the benefits meet their needs, and would recommend the program to peers. This can surface issues like confusing reimbursement processes before they show up in turnover data.
Common pitfalls to avoid:
If your current vendor can't surface real-time utilization data or requires manual reporting, that's a signal worth acting on before the next plan year.
Choose the right model or combination of models, design your menu around actual employee needs, select a vendor that can support the full scope without creating disconnected systems, and set measurable targets before you launch.
The employers who get the most out of flexible employee benefits aren't necessarily the ones with the largest budgets. They're the ones who've built programs their employees actually understand and use. That starts with an honest assessment of whether your current benefits stack can support the flexibility, compliance requirements, and administrative efficiency your workforce expects.
Ready for a more configurable program? Explore how Benepass can help you improve participation and manage costs more effectively, with pre-tax accounts, lifestyle benefits, and wellness programs on a single platform.
The terms are functionally identical. Both describe an employer-sponsored program that lets employees choose benefits from a menu rather than receiving a fixed package.
"Scheme" is more common in the UK and Commonwealth countries, while "plan" is the standard term in the US, particularly in IRS documentation and Section 125 compliance guidance. The underlying mechanics, tax treatment, and design principles are the same regardless of what you call it.
Flexible benefits schemes are available to employers of all sizes, and adoption is growing as platforms make administration more accessible. Today, employers with as few as 10 employees can offer Section 125 cafeteria plans, HSAs, HRAs, and lifestyle spending accounts without needing in-house benefits expertise.
Pre-tax health insurance plans like FSAs, HSAs, and HRAs reduce taxable wages for both employees and employers, lowering FICA contributions and generating payroll tax savings. Post-tax programs like LSAs and employer stipends are treated as taxable compensation and reported as wages on W-2s.
Each account type carries its own compliance requirements: Section 125 plans require annual nondiscrimination testing and plan documents, HSAs must be paired with a qualifying HDHP, and HRAs are subject to ACA, ERISA, and HIPAA rules. Most employers work with a benefits administration platform to manage documentation, eligibility, and reporting in one place rather than coordinating across multiple systems.